Bausparvorteila service by INTERNA

OUR ADVICE BRINGS YOU MONEY FROM THE STATE

The German state adds money to your savings. From 2027, a lot more.

In the news it is called “Eigenheimrente”. What it means: you save every month in a home savings contract (Bausparvertrag), and the state adds money every year. Up to €540 for you and €300 for each child.

since 1985only government subsidies
176,000people helped to get subsidies
Your languageadvice in your mother tongue

Last updated:

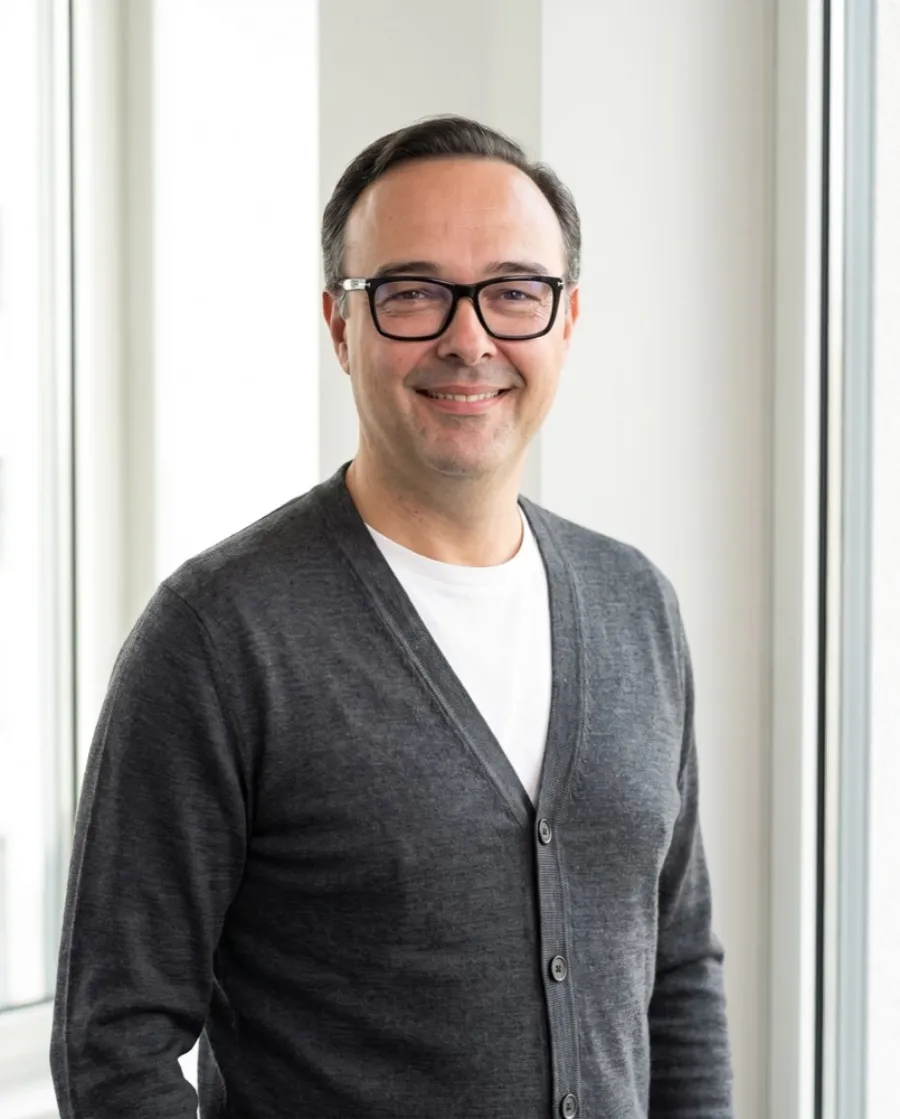
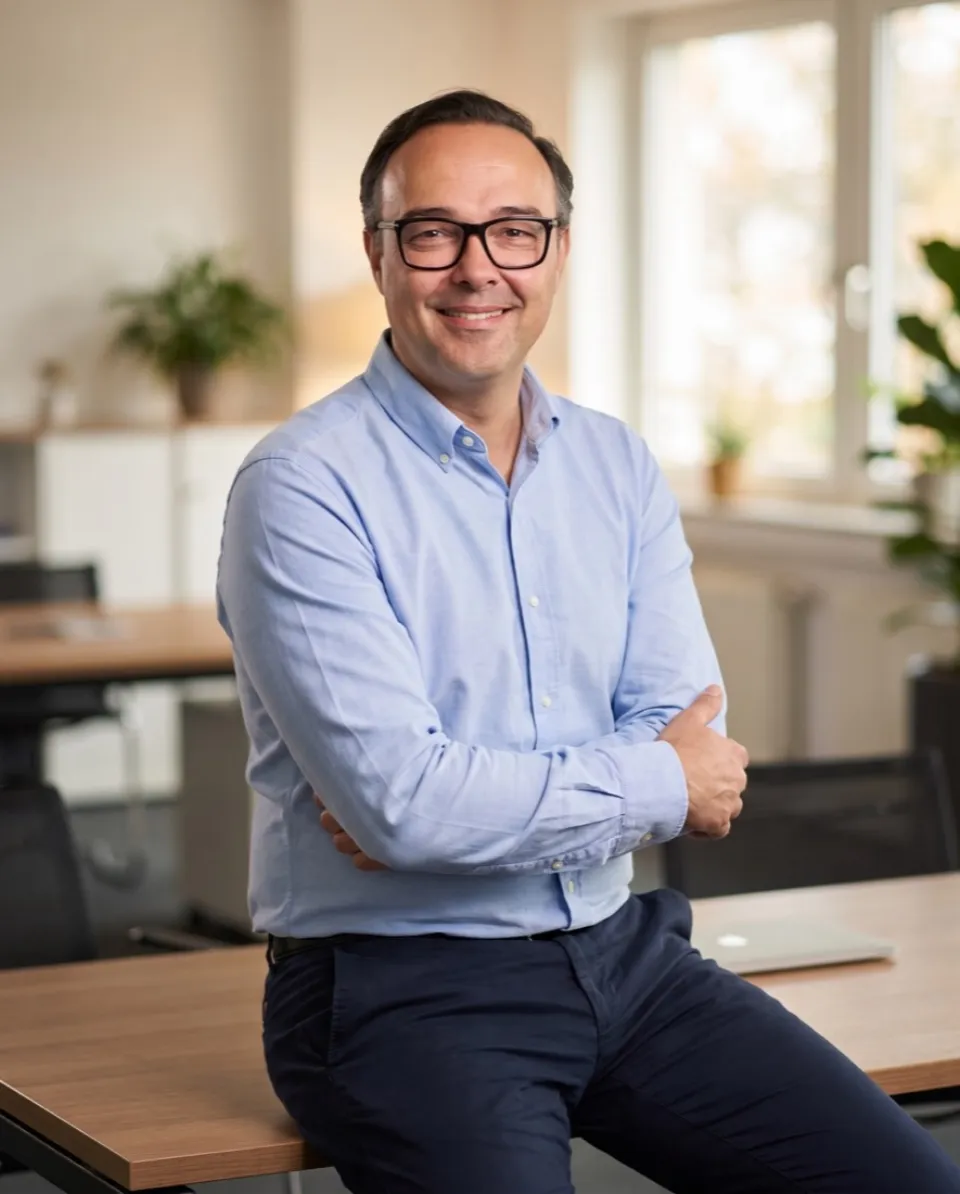
Marc A. Schnitzler, Managing Director of INTERNA, smiling in the office
“Many people don’t even know this money is theirs. We explain it calmly and take care of the rest.”Marc A. Schnitzler, Managing Director

Advice in your language

Our advisors speak German, English, French, Turkish, Bosnian, Croatian, Serbian, Montenegrin and Albanian. Tap your flag to see this page in your language.

IN SHORT, WITHOUT JARGON

Three questions, three answers. Then you know what it is about.

1

What is it?

A normal home savings contract where the state saves with you. From 2027 new rules apply and the subsidies rise sharply.

2

What do I get?

Up to €540 a year for every adult who saves, from just €10 a month. €300 extra for each child, without paying in anything extra for the child. Every year, as long as you save.

3

What do I have to do?

Calculate your subsidy and register your interest. Your advisor will contact you, explain everything and make sure you are in from day one. We fill in the application together with you.

This is how much the state adds for you:

€5you put aside each day
€540the state adds each year
€300more for each child, every year

€5 a day is €150 a month. If you put aside less, you get proportionally less, starting from €10 a month. Example based on the new law from 1 January 2027.

WHAT DO I NEED IT FOR? WHAT DOES IT BRING ME?

Do you recognise yourself? Six life situations, six examples.

Paying off a loan, saving for a deposit, modernising, or simply getting started. Nobody has to know today what life will look like in ten years. You still get the subsidy.

Young family painting a wall in their flat togetherAI image
“I AM STILL PAYING OFF MY LOAN.”

The state pays part of your remaining debt.

Your loan continues, whatever the bank. You save alongside it. When the remaining debt is small enough, you pay it off with your savings.

Single parent, one child, €150 a month, 10 years
You pay in€18,000
The state adds€8,400
Available to repay€26,400
Almost a third of it comes from the state.
“I WANT TO BUY ONE DAY.”

Build your deposit faster, because the state saves with you.

The subsidies count as equity when you finance. The savings go into buying or building your own home.

Couple, both working, one child, €150 each a month, 5 years
You pay in€18,000
The state adds€6,900
Your equity€24,900
“I WANT TO MODERNISE.”

Heating, windows or a step-free shower, with money from the state.

Work from €3,000 is possible, before it was €6,000. You can also use grants from the state funding banks KfW and BAFA.

Single, €100 a month, 4 years
You pay in€4,800
The state adds€1,560
For modernising€6,360
“I DON’T KNOW YET IF I WILL BUY.”

Take the subsidy now, decide later.

If you buy after all, the savings go into the property. If you never buy, the money is not lost: you receive it in old age as an extra pension, part of it at once.

Employee, two children, €150 a month
Subsidy for herself€540
Subsidy for the children€600
From the state, every year€1,140
“I AM YOUNG AND JUST STARTING OUT.”

Start early, lots of subsidy for little money.

Under 25? You get a one-off €200 extra in the first year. Starting at 20 and buying at 28 works too: €150 a month adds up to about €18,900 of equity.

Age 24, apprentice, €50 a month, 10 years
You pay in€6,000
The state adds€2,600
Starting capital€8,600
More than 40 euros of subsidy on every 100 euros you save.
“WE ARE A COUPLE AND BOTH WORK.”

Each of you gets your own subsidy, with your own contract.

The state supports each of you separately. For that, each of you needs your own contract and pays in yourself. With only one contract you leave €540 a year on the table.

Couple, both working, one child, subsidies per year
Only one pays €150€840
Both pay €150 each€1,380
Extra with two contracts€540
Over ten years that is €5,400 more.

THE BASIC RULE

€150 a month brings €540 a year. €300 more for each child.

No extra payment for the child. This is what you get per year:

Calculate my subsidy

You savefor youper child
€10€60€120
€25€150€300
€50€240€300
€100€390€300
€150€540€300

Examples based on the law from 1 January 2027, without interest and without tax benefits. The child subsidy is paid as long as you receive child benefit (Kindergeld). Self-employed people can use all options too.

SUBSIDISED TWICE

Two contracts, twice the money from the state.

Does your employer pay “vermögenswirksame Leistungen”, money for saving on top of your wages? Then a second, normal home savings contract is worth it. Both subsidies run side by side.

CONTRACT 1: SUBSIDISED HOME SAVINGS

Your own money

You save €150 a month
€1,800
Subsidy for you
€540
Subsidy for one child
€300

per year

CONTRACT 2: NORMAL HOME SAVINGS

Money from your employer

Employer pays €40 a month
€480
Employee savings bonus from the state
€42.30
Housing bonus if you pay in more
up to €70

per year

For €1,800 of your own money, about €3,160 a year lands in your contracts: €480 from your employer and €882.30 from the state.

The employee savings bonus (Arbeitnehmersparzulage) applies up to €40,000 taxable income (couples €80,000), the housing bonus (Wohnungsbauprämie) up to €35,000 (couples €70,000, bonus up to €140). Your taxable income is shown in your tax assessment. Your employer pays “vermögenswirksame Leistungen” if your employment or collective agreement provides for them. We help you ask.

THE HONEST ANSWER

Do I have to pay everything back in the end?

No. The subsidies are yours as long as you use the money for your own home or your retirement. In old age you pay tax on it, like on any pension, usually at a low rate.

If you …Pay subsidies back?What happens instead
… use the money to buy, build, repay or moderniseNoThe amount is taxed over 5 years from retirement.
… never buy and take the money as a pension in old ageNoThe pension is taxed in old age.
… switch provider or transfer the contractNoYou keep the subsidy.
… sell the property before the commitment ends or move out for goodNoThe remaining amount is taxed at once, unless you buy a new home of your own within the deadlines.
… cancel and simply take the money outYesThe state reclaims the subsidies.
… have to repay all child benefit for a childYes, for that yearThe child subsidy for that year goes back.

Only people who cancel and use the money for something else, or who were not entitled, have to pay back.

Example life situation 1: the €26,400 are taxed over 5 years in old age, i.e. €5,280 a year. At a 20 % tax rate that is about €5,280 of tax in total, compared with €8,400 of subsidies. Our own illustration, not tax advice.

WHAT TO DO WHEN

Register today. Be in from day one.

There is no rush. But if you register now, you start in January without waiting.

  1. TODAY

    Calculate your subsidy and register

    Your advisor gets to know your situation. If your employer pays “vermögenswirksame Leistungen”, we also check whether you are entitled to the employee savings bonus or the housing bonus.

  2. 1 JANUARY 2027 · 96 DAYS TO GO

    The new subsidy starts

    From now on the higher subsidies apply. If you start with the first instalment in January, you spread the yearly amount over twelve small instalments and get the subsidy for all of 2027.

  3. EVERY YEAR AFTER

    The state pays in

    The subsidy goes into your contract. From 2028 you can withdraw savings under the new rules for your home. If something changes, for example a child is born, we adjust it with you.

Do you already have a Riester contract? It continues as before. Important: if you take out a new subsidised contract from 2027, all your old contracts automatically switch to the new system. That is not good for everyone, for example with a very low income. So we calculate both options with you first.

YOUR SUBSIDY CHECK

How much will the state add for you?

Six questions to tap, no documents needed. Afterwards you know:

  • how much subsidy you are entitled to each year
  • how much adds up in ten years
  • what happens next and who advises you
Marc A. Schnitzler explains the subsidy to a young family at the kitchen table
Subsidy checkStep 1 of 6
Marc A. Schnitzler, Managing Director of INTERNA

A PERSONAL WORD

“This money is yours. We make sure you actually get it.”

Since 1985, this is all we do at INTERNA: we help families and employees get government subsidies. Many people have never heard of them, or the forms put them off. That is exactly why we are here.

Our advisors speak your language, come to you and take their time. They explain everything until it is clear. And they remain your contact, even years later.

Marc A. Schnitzler
Managing Director, INTERNA Vermittlungsgesellschaft für Bausparen und Finanzierungen mbH

1985founded, only subsidies ever since
176,000people helped to get subsidies
38,000families helped into their own home with partners
~70advisors, many of them multilingual

FOR WHOM

From 2027 many more people can take part.

Families

You get €300 a year for each child, without paying in extra. From €25 a month the full child subsidy is included.

Self-employed

Restaurant, trade business or shop: from 2027 self-employed people without compulsory pension insurance are eligible too, with a tax return and up to age 67. The same goes for doctors, lawyers and other members of professional pension schemes.

Young people

With €30 a month you get €180 subsidy a year, half your contribution. Under 25, a one-off €200 extra.

Employees and civil servants

The full subsidy no longer depends on your income. You are in from €10 a month.

FOR CAREFUL READERS

Before and from 2027 compared

WhatBeforeFrom 2027
Subsidy per person€175 a yearup to €540 a year
Subsidy per child€185 for children born before 2008, €300 from 2008up to €300 for every child
Who is eligibleEmployees and self-employed people paying into the state pension, civil servants and some other groupsalso self-employed people without compulsory pension insurance and members of professional pension schemes, up to age 67
Own contribution4 out of every 100 euros of your income for the full subsidyindependent of income, from €10 a month
Tax in retirementspread over 20 years, amount grows by 2 % a yearspread over 5 years, no yearly increase

Source: German Federal Ministry of Finance, questions and answers on the reform of private pensions.

Frequently asked questions

Can I do something today?

Yes. Have your subsidy calculated and register. We also check whether you are already entitled to the housing bonus or the employee savings bonus today. These run through a second, normal home savings contract.

When can I use the money for my home?

Under the new rules from 1 January 2028. Then you can withdraw all your savings, for buying, building, modernising from €3,000 or paying off your loan.

What if I never buy a property?

Then you receive your savings in old age as monthly payments. You can take up to 30 % at once. You keep the subsidy.

Do I have to live in the property myself?

Yes. If you withdraw savings for your home, you should live there until 5 years after your payouts start in old age, so until about 72 if they start at 67. After that you may sell or rent it out. If you move earlier and buy a new home of your own within the legal deadlines, you keep the subsidy. Otherwise the remaining amount is taxed at once. Even then you do not have to pay back the subsidies.

What if I can no longer save for a while?

You can lower or pause your contribution. €10 a month is enough for the subsidy. Do not cancel: then the state reclaims the subsidies. Your advisor will find a solution with you.

Does it work together with “vermögenswirksame Leistungen”?

Yes, with a second contract. The money from your employer and the housing bonus go into a normal home savings contract, your own contribution into the subsidised one. That way you use both subsidies.

Is the child subsidy paid forever?

It is paid for every year in which you receive child benefit (Kindergeld) for the child. After that your own subsidy remains.

Do I have to buy shares or funds?

No. We offer the subsidy only with a home savings contract, with a fixed interest rate and no market risk.

I already have a Riester contract. What happens to it?

Contracts signed by 31 December 2026 keep the old rules. You can switch voluntarily. The switch is then permanent and applies to all your contracts. We calculate both options with you first.

Is it worth it on a small income?

Usually yes. Until now, €60 a year was enough for the full subsidy. People who earn very little and already have an old contract are sometimes better off with it. Your advisor checks this with you.

Do I have to pay tax on the subsidy later?

Yes, in retirement. The tax office keeps a separate account for your contract with your subsidised contributions and subsidies. From 2027 this amount is taxed over 5 instead of 20 years and no longer grows by 2 percent a year. We do not give tax advice. For your individual case, please ask your tax advisor.

Will I ever have to pay the subsidies back?

Only if you cancel and use the money for something else. If you use it for your home or as a pension, the subsidies are yours. The overview “The honest answer” above shows all cases.

Sources

Last updated:

How much will the state add for you?

One minute, six taps. No obligation and no documents.

Note on artificial intelligence

This page uses images created with artificial intelligence. The portraits of Marc A. Schnitzler are based on real photos and were created with his consent. The family scenes are illustrations. Texts and translations were created with the help of artificial intelligence. The subsidy check calculates using fixed rules and makes no automated decisions about you. More about how we use AI

Check my subsidy